You're standing at the checkout with groceries, toothpaste, and a scented candle in your basket. You need dinner and basic hygiene supplies. The candle would make your evening nicer, but buying it also means having less money available for something else.
That small decision is the starting point for a useful budget. Needs protect your health, safety, housing, or ability to earn a living. Wants add comfort, convenience, or enjoyment without being essential. Neither category says anything about whether you're a responsible person.
The tricky part is that the same purchase can serve different purposes. A car might be necessary for a rural commute but optional for someone who lives beside reliable transit. A prepared meal might be a treat one evening and a practical accommodation during illness.
- Purpose matters more than the store. A supermarket receipt can include both essential food and optional purchases.
- An essential expense can still be adjustable. You might need internet service without needing the fastest package.
- Wants belong in a realistic budget. The question is whether you can afford them without leaving necessities unpaid.
These needs vs wants examples use familiar spending categories, from rent and groceries to childcare and gifts. Each comparison gives you a rule you can apply to purchases beyond the examples themselves.
1. Needs vs Wants Examples for Groceries, Rent, and Everyday Spending
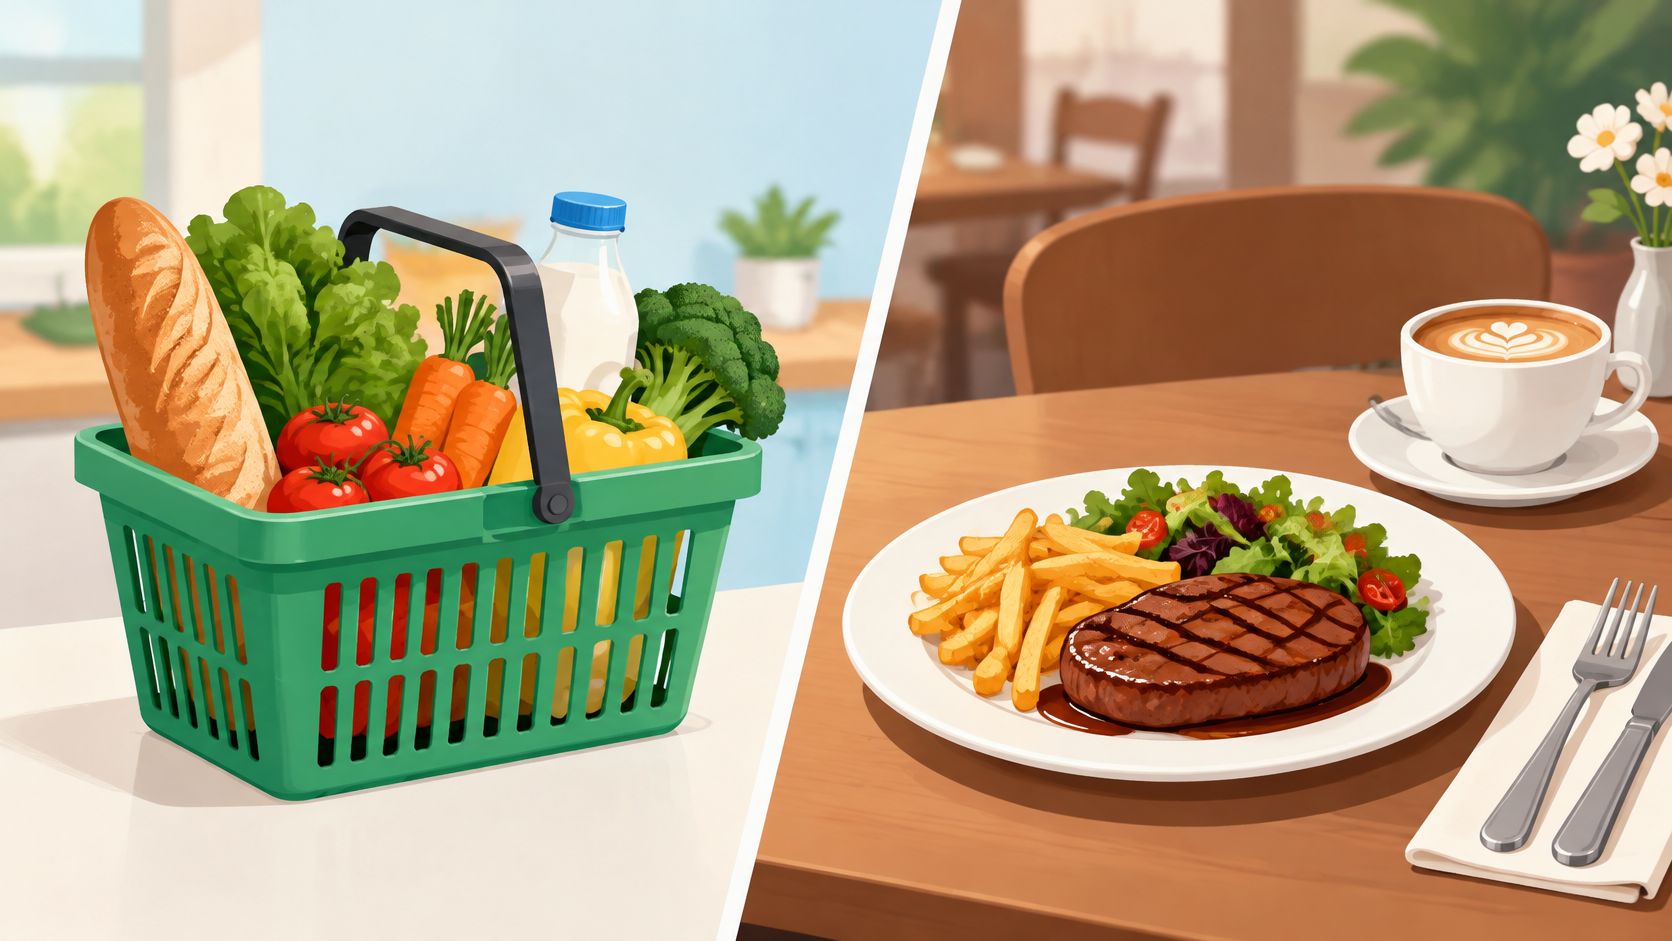
A grocery shop and a restaurant meal both provide food. That doesn't automatically make them equivalent budget priorities.
The Financial Consumer Agency of Canada's budgeting guidance identifies shelter, clothing, food, and medication as needs, while restaurant meals, trips, gym memberships, and designer shoes are wants. Classify what the purchase does for you, not just what it costs.
Separate the basic requirement from the extra
- Food: Ingredients for meals are usually a need. A restaurant meal chosen for enjoyment is generally a want.
- Connectivity: Internet required for work or school is a need. An additional streaming subscription usually isn't.
- Clothing: A winter coat that protects you from the cold is a need. A designer replacement for a serviceable coat is a want.
Say you stop at a pharmacy for a prescription and add a decorative mug. Record the medication under necessary health spending and the mug under discretionary shopping, even though they appear on the same receipt.
Your first budgeting action is to review recent purchases and separate essential costs, adjustable essentials, and optional extras. Include cash purchases so your spending record reflects what happened.
Required debt payments also belong among your obligations. Paying extra toward debt is a separate planning decision, not permission to leave rent, food, or medication unfunded.
2. Needs vs Wants Examples for Housing and Home Expenses
Safe shelter is a need. Every improvement to that shelter isn't. Rent or mortgage payments, applicable property taxes, basic utilities, necessary repairs, and home insurance generally protect your ability to remain safely housed.
California illustrates why housing deserves attention before you blame discretionary spending. The Bureau of Labor Statistics' comparison of consumer spending found that housing accounted for about 37% of California household spending, compared with roughly 33% nationally.
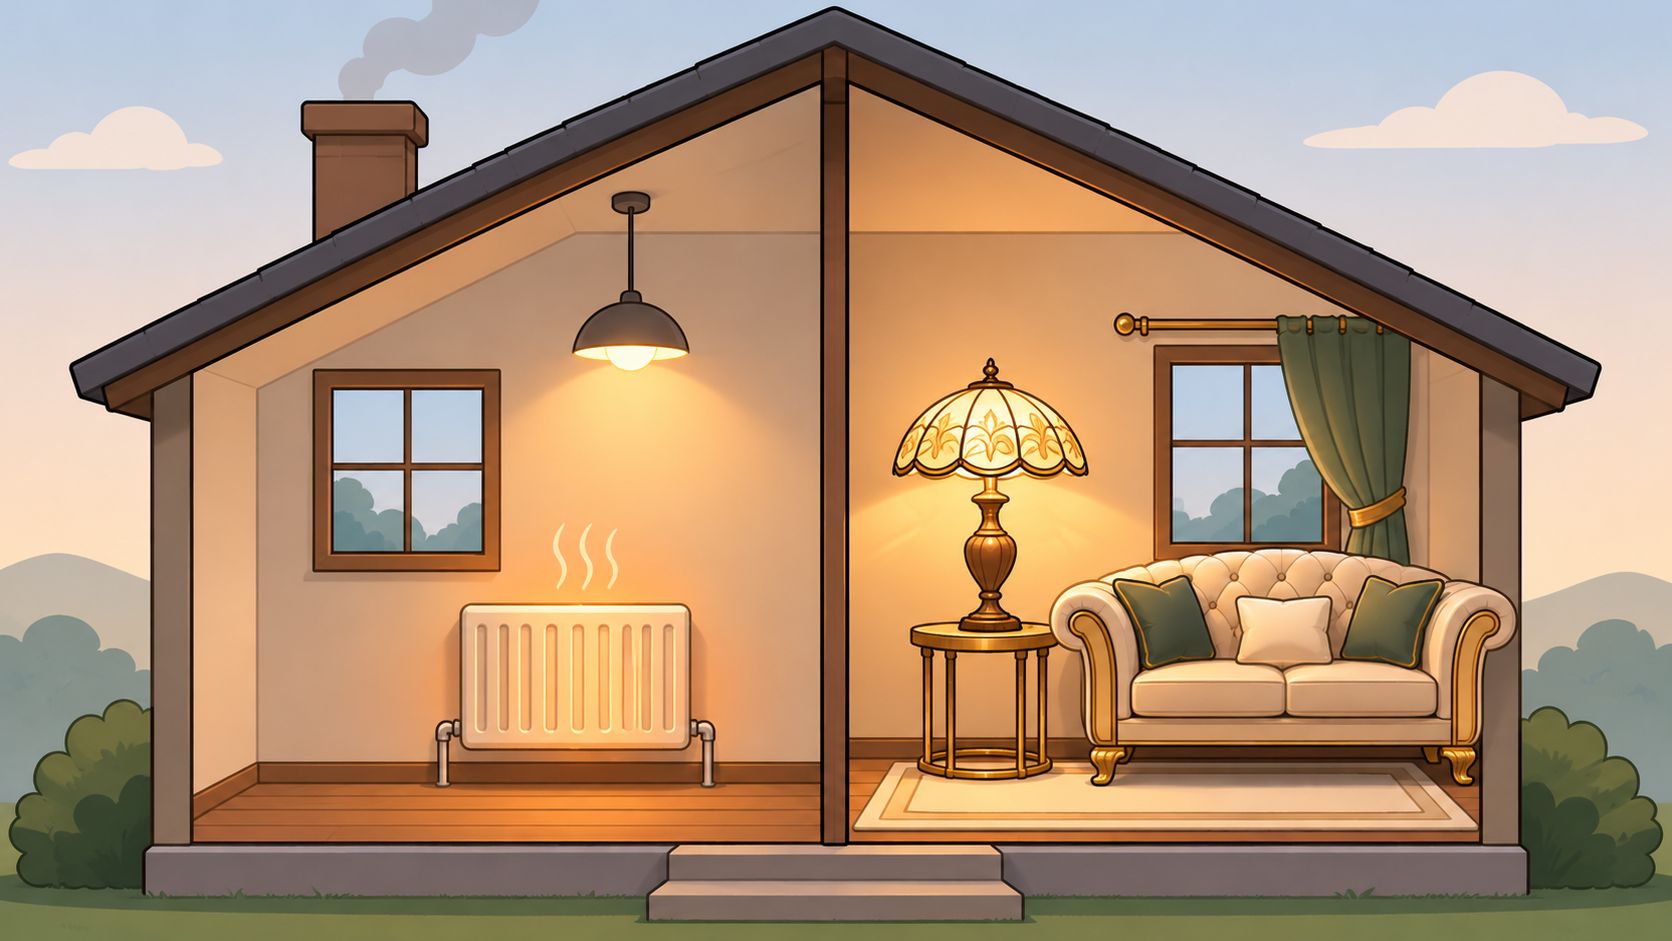
- Repair versus renovation: Fixing a leaking faucet protects the home. Replacing a working bathroom with a spa-style renovation is generally optional.
- Function versus appearance: A usable mattress can be essential. A decorative bed frame usually isn't.
- Service versus upgrade: Heat and electricity meet basic needs. Smart lighting and premium appliances usually add convenience.
Say your refrigerator stops keeping food cold. A suitable replacement meets a need, but choosing an expensive model for its display screen adds a discretionary component.
Practical rule: Ask whether the expense prevents an unsafe or unusable home, or mainly makes a functioning home more attractive.
Use guidance on how much to spend on rent when assessing affordability. If you're responsible for improvements, compare rental property upgrades by cost without assuming every upgrade is necessary or permitted under your lease.
3. Needs vs Wants Examples for Transportation Decisions
Would you still need the trip if you weren't buying anything or going somewhere for fun? That question helps distinguish essential mobility from optional convenience.
The Financial Consumer Agency of Canada's Financial Basics handbook explains that a car can change from a want to a need when someone requires it to commute or perform their job. A practical alternative must work with your schedule, accessibility requirements, and caregiving responsibilities.
Judge the journey and the vehicle separately
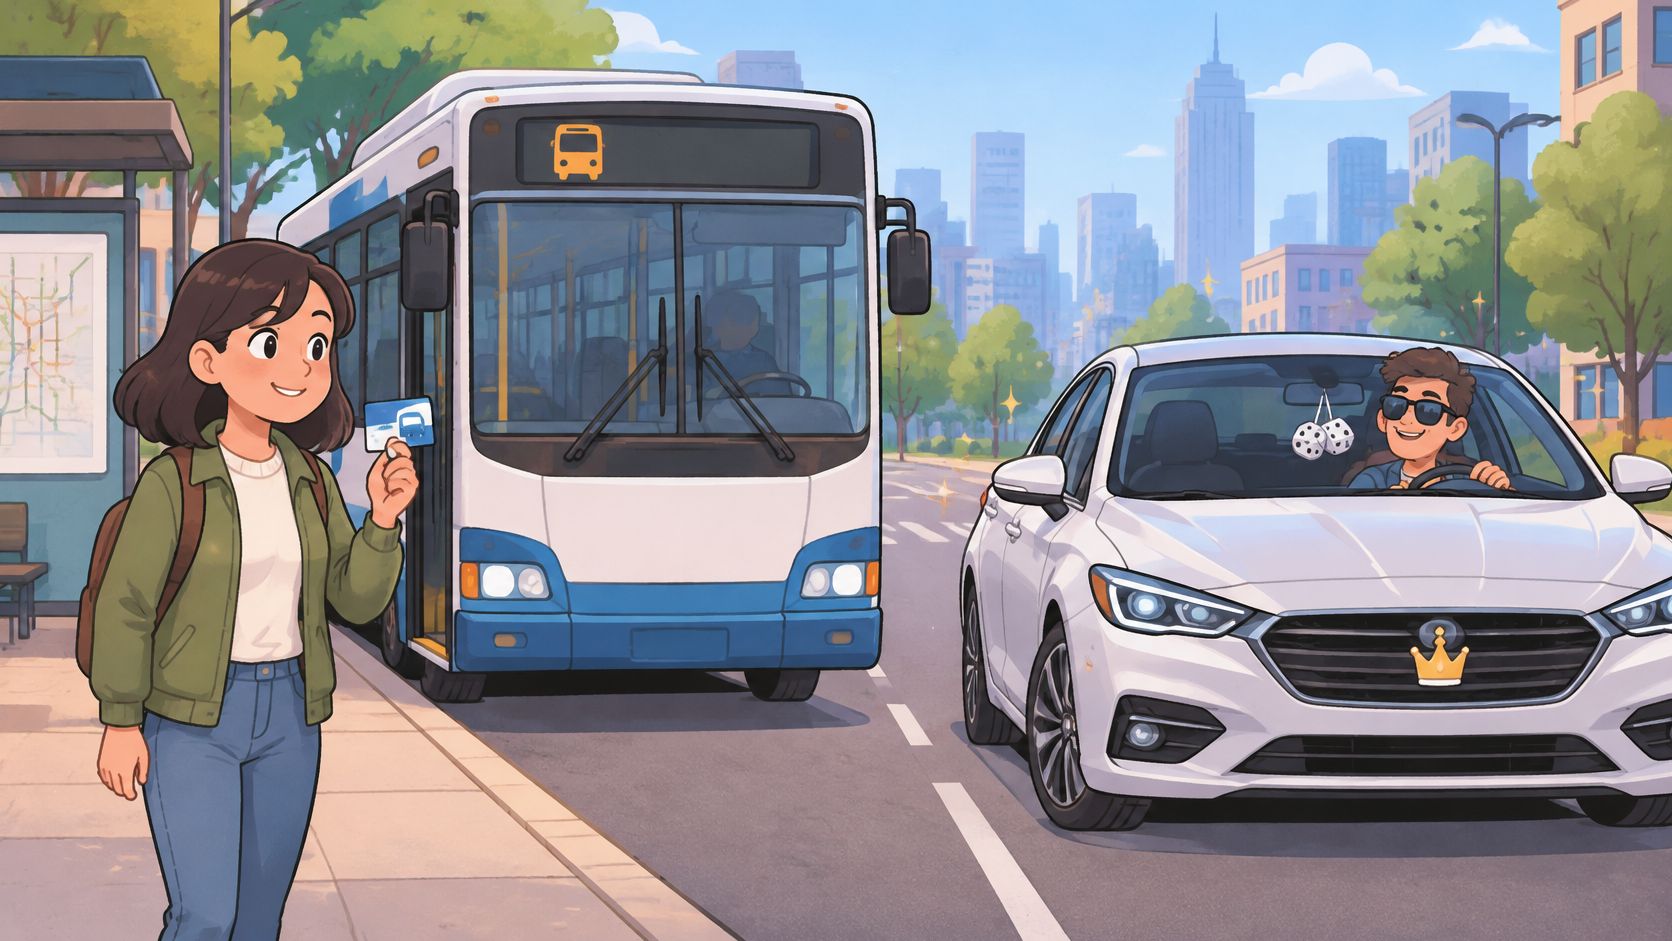
A bus pass for work is generally a need. So are necessary fuel, vehicle insurance, registration, and maintenance when driving is your realistic way to reach essential destinations.
A luxury trim package, decorative accessories, and convenience rides when suitable transit is available are usually wants. Use the fuel grade your vehicle requires, rather than assuming premium fuel is always necessary or always optional.
- Safety requirement: Winter tires appropriate for your driving conditions can be a need.
- Optional enhancement: Decorative car mats are generally a want.
- Mixed purchase: A necessary replacement car can include optional upgrades.
Say a parent needs a reliable vehicle for work and daycare pickups. The transportation need is real, but it doesn't automatically justify a larger vehicle or premium features.
Review insurance, parking, maintenance, and financing together before replacing a car. The 20/4/10 car affordability framework can support that review, but your actual essential costs still determine what's manageable.
4. Needs vs Wants Examples for Groceries, Dining Out, and Food
A single food category can hide very different decisions. Infant formula, pantry staples, and medically necessary dietary foods don't serve the same purpose as delivery fees or specialty drinks.
The Bureau of Labor Statistics' Los Angeles household spending release reports that, within food spending in 2023–24, 55.2% went to food at home and 44.8% to food away from home. Separating those categories makes the adjustable portion easier to identify.
- Weekly meals versus restaurant lunches: Groceries for planned meals usually meet a need; restaurant lunches are generally wants.
- Nutrition versus preference: Medically necessary nutrition is a need; a bottled drink chosen for enjoyment usually isn't.
- Ingredients versus convenience: Meal kits include food, but their convenience component may be discretionary.
Make the alternative realistic
Say you repeatedly order dinner after late shifts. Don't build a plan that assumes you'll suddenly cook elaborate meals every evening; keep practical options such as frozen vegetables, canned beans, and ready-to-heat meals available.
Convenience isn't automatically wasteful. Disability, limited kitchen access, illness, and caregiving can change what adequate food preparation requires.
Use a guide to monthly grocery costs for one person as a planning reference, not a personal spending verdict. Then plan affordable weeknight dinners ahead, set a grocery target before shopping, and track restaurants and delivery separately.
5. Needs vs Wants Examples for Health Care and Wellness
Don't cut necessary care because an optional wellness purchase appears in the same spending category. Health care and lifestyle spending need separate treatment.
Prescriptions, necessary dental care, mental health support, and preventive care generally belong among needs. Spa visits, cosmetic treatments, and premium fitness experiences are usually wants unless your circumstances establish a specific health requirement.
Compare the purpose, not the health label
- Medication versus membership: A prescribed refill is a need. A premium gym membership is generally optional.
- Dental care versus appearance: A cleaning needed for oral health differs from cosmetic whitening.
- Treatment versus experience: Necessary therapy differs from a meditation retreat chosen for relaxation.
Say you're paying for therapy and an unused fitness membership. Cancelling the unused membership is a sensible review step; stopping treatment because both expenses fall under wellness isn't.
Don't treat a product's wellness branding as proof that you need it, or treat necessary care as a luxury because it's expensive.
Check employer benefits, insurance coverage, and applicable public programmes before paying out of pocket. Coverage differs across Canada and the United States, so confirm the terms that apply to your situation rather than assuming a service is covered.
Keep notes that distinguish required care from optional purchases. If you're considering changing medication or treatment because of cost, discuss appropriate alternatives with your clinician or pharmacist rather than making the change solely to meet a budget target.
6. Needs vs Wants Examples for Entertainment and Subscriptions
You use a streaming service every week. Does that make it a need? Regular use can make a want worthwhile without making it essential.
Movies, gaming, concerts, hobbies, and leisure subscriptions usually belong in discretionary spending. They can still support family connection, cultural participation, and enjoyment, so the useful question is whether they fit safely into your budget.
The Public Policy Institute of California's economic well-being survey found that 19% of Californians said paying an emergency expense of $1,000 would be very difficult or nearly impossible. That's a reason to protect a financial buffer, not an argument that everyone must abandon enjoyable activities.
Keep the entertainment you actually value
Say your household watches one service regularly while several others renew unnoticed. Keep the service you enjoy if it fits your allowance, and review the rest individually.
- Check necessity: Is this leisure, or a service required for work or accessibility?
- Check frequency: Are you using it enough to justify keeping it?
- Check replacement value: Does it replace a more expensive activity you'd otherwise buy?
- Check priorities: Would cancelling it meaningfully support an urgent goal?
A free subscription-tracking approach can help you make that inventory. Separate intentionally planned entertainment from subscriptions you're paying through habit, and assign any actual savings to a clear purpose.
7. Needs vs Wants Examples for Clothing, Personal Care, and Shopping
Your work shoes have split soles, but the shop also has sneakers you've wanted for months. Both purchases belong under clothing; only one addresses the immediate problem.
Replacement, suitability, and what you already own are better classification tests than whether an item is fashionable or on sale. A discount doesn't create a need.
- Work requirement versus collection: Reliable shoes suitable for your job are usually a need. Another pair bought mainly for style is generally a want.
- Basic hygiene versus premium preference: Toothpaste meets a need. An expensive imported version usually adds an optional premium.
- Weather protection versus expansion: A suitable winter coat is a need if you don't have one. Expanding an already functional wardrobe is a want.
Check the gap before filling the basket
Say you need clothing for a new job. Start with the dress requirements and items already in your wardrobe, then buy what's missing rather than replacing everything.
The same principle applies to personal care. Products required for a skin condition or accessibility need shouldn't be treated like optional beauty purchases just because they're sold beside them.
Before buying a non-essential item, use a waiting period and check whether you already own something that performs the same job. Choose your own spending threshold for that pause, based on your budget rather than a universal rule.
Record necessary replacements separately from lifestyle shopping. That makes it easier to reduce discretionary purchases without postponing worn-out essentials.
8. Needs vs Wants Examples for Travel and Vacation Spending
A flight to receive necessary medical treatment and a flight to a resort may look identical on a bank statement. Their purposes are different.
Essential work travel, necessary medical travel, and some family obligations can be needs. Holidays and leisure upgrades are generally wants, even when you've been looking forward to them for a long time.
Separate the necessary trip from optional extras
- Reason for travelling: A necessary medical appointment differs from a vacation.
- Accommodation: A suitable room during essential travel can be a need. Upgrading to a luxury suite is usually a want.
- Baggage and seating: What's necessary depends on medical, accessibility, equipment, and travel requirements, not just the airline's basic fare.
- Protection: Appropriate travel insurance can be prudent. Review coverage rather than automatically accepting every add-on.
Say you must travel for treatment. Nearby accommodation may be more practical than a cheaper room that creates difficult transportation demands, while a room upgrade for its view remains optional.
Budget boundary: A necessary trip doesn't turn every purchase made during that trip into a need.
For leisure travel, build a sinking fund, money reserved gradually for a planned expense. Review transportation, accommodation, meals, insurance, and activities before deciding the trip is affordable.
A practical guide to budgeting for a trip can help you capture those costs. After returning, compare what you planned with what you spent and use the difference to improve your next target.
9. Needs vs Wants Examples for Kids, Family Obligations, and Childcare
Childcare that enables a parent to work is usually a need. A private club membership usually isn't, even when both help a family organise its week.
Children's ages, disabilities, school requirements, and caregiving arrangements affect the distinction. Don't classify an expense solely by whether another household can manage without it.
The Public Policy Institute of California's California Poverty Measure put the average poverty threshold for a two-adult, two-child family at approximately $46,200 in 2024, accounting for local housing costs and other essential expenses. That's a context-specific measure, not a spending target for every family.
- School requirement versus hobby upgrade: Required supplies are needs. Premium art materials for an optional hobby are generally wants.
- Basic clothing versus celebration extras: Suitable clothing is a need. An elaborate costume usually isn't.
- Transportation versus recreation: A bicycle used to reach school may meet a need; one bought mainly for leisure usually serves a want.
Make shared decisions before shopping
Say your child needs school supplies and also wants a science kit. Fund the required supplies first, then assess the kit within the family's discretionary allowance.
When picking between microscopes and robotics kits, consider interest, suitability, and likely use. Educational value can make a purchase worthwhile without making it mandatory.
List seasonal requirements ahead of time and agree on activity limits together. This helps caregivers distinguish genuine obligations from upgrades purchased under pressure.
10. Needs vs Wants Examples for Giving, Gifts, and Social Spending
An invitation arrives for a birthday dinner, and you feel you have to attend, bring a gift, and contribute to a group present. Those expectations can feel compulsory without being basic financial needs.
Gifts, donations, celebrations, and most social outings are wants. They can still rank highly among your priorities because relationships, traditions, and personal values matter.
Decide what matters before deciding what to spend
- Birthday gift versus basic obligation: A present is generally discretionary, even when declining feels uncomfortable.
- Donation versus essential bill: Giving to a valued cause can be important without taking priority over rent or medication.
- Celebration versus competing want: An anniversary dinner may matter more to you than shopping or another leisure purchase.
Say you want to attend a friend's wedding but can't comfortably afford every related event. You might attend the ceremony, decline an optional trip, and choose a gift within your means.
For predictable occasions, reserve money throughout the year rather than treating each event as a surprise. The Financial Consumer Agency of Canada's budgeting guidance for irregular expenses recommends converting periodic expenses into regular amounts you can set aside.
Agree on per-person or per-event limits before shopping. A gift card, shared experience, or modest practical gift can work when it suits the recipient, but the right choice doesn't require exceeding your allowance.
Keep giving visible in your budget so generosity remains a deliberate choice rather than an expense you discover afterwards.
Needs vs Wants at a Glance Across 10 Everyday Spending Categories
| Category | Typical Needs | Typical Wants | Classification Rule | Best Budget Move |
|---|---|---|---|---|
| Everyday spending | Groceries, housing, utilities, health care, insurance, debt payments | Restaurant meals, entertainment, premium coffee, travel upgrades | Judge the purchase by its purpose and your circumstances; essentials support basic living or stability. | Track purchases and review flexible spending before cutting essentials. |
| Housing and home expenses | Rent or mortgage, utilities, insurance, necessary repairs | Luxury finishes, decorative items, smart-home upgrades | Prioritize safe shelter and repairs that prevent or fix essential problems. | Fund required housing costs and repairs before optional upgrades. |
| Transportation | Work transit, necessary fuel, insurance, registration, safety maintenance | Larger vehicles, decorative accessories, convenience rides | Consider the trip's purpose, safety needs, and available alternatives. | Review total monthly transport costs and trim recurring convenience spending. |
| Groceries, dining, and food | Groceries, pantry staples, medically necessary foods | Restaurant meals, delivery, specialty drinks, premium snacks | Separate food required for nutrition or health from convenience and leisure choices. | Use distinct grocery, restaurant, and delivery categories and set a grocery target. |
| Health care and wellness | Prescriptions, medical visits, dental care, necessary therapy | Luxury fitness classes, cosmetic procedures, spa treatments | Protect necessary care; treat optional wellness purchases as flexible unless medically recommended. | Keep health care separate from optional wellness spending and review unused memberships. |
| Entertainment and subscriptions | No typical basic need; some activities may support well-being or connection | Streaming, concerts, movies, gaming, hobbies | Usually discretionary, but weigh personal value and use rather than treating every want as expendable. | Audit subscriptions regularly and redirect cancelled costs toward savings goals. |
| Clothing and personal care | Work or weather-appropriate clothing, hygiene essentials, accessibility items | Trendy apparel, luxury beauty products, duplicate purchases | Compare the purchase with actual needs, existing items, and expected use. | Check what you already own and pause before nonessential purchases. |
| Travel and vacation | Required work, medical, family, or return-home travel | Vacations, luxury lodging, premium seating, souvenirs | Classify by the trip's purpose; separate essential travel costs from upgrades and leisure extras. | Save in advance, plan the base cost first, and limit add-ons. |
| Kids, family, and childcare | Childcare, food, medical care, school supplies, required clothing | Luxury toys, private clubs, optional lessons, elaborate entertainment | Consider the child's needs, family circumstances, and whether the expense is required or an optional enhancement. | Fund mandatory family costs first and agree on a shared discretionary limit. |
| Giving, gifts, and social spending | No typical basic need; some commitments may be personally important | Gifts, donations, weddings, social events | These are generally discretionary, though values and relationships may make them priorities. | Set limits ahead of occasions and include recurring traditions in the yearly budget. |
Turning the Need-or-Want Test Into a Working Budget
You don't need a perfect label for every purchase. You need a consistent way to decide what to protect, what to adjust, and what can wait.
Use this test before buying and when reviewing transactions:
- Name the purpose. Does the purchase protect health, safety, housing, essential caregiving, or your ability to earn?
- Check a reasonable alternative. Could a lower-cost option meet the same requirement without creating an unrealistic burden?
- Separate the upgrade. If the basic purchase is necessary, identify any optional features or convenience costs.
- Decide before pressure takes over. Set your boundary before entering the shop, accepting the invitation, or opening the delivery app.
Fund needs first, but distinguish fixed obligations from flexible essentials. Rent may be difficult to change immediately, while grocery choices, utility usage, or a phone package may offer room to adjust.
Don't force essential spending into an arbitrary share of income. If necessities already use most of your take-home pay, acknowledge that constraint and review larger recurring costs alongside discretionary purchases, rather than cutting adequate food or necessary care.
Give wants and savings clear jobs
Set explicit limits for restaurants, shopping, entertainment, and other flexible categories. Keep an allowance for the things you value, then direct reductions you can sustain toward savings or debt repayment.
The Financial Consumer Agency of Canada's emergency-fund guidance recommends aiming for three to six months of regular expenses or income, while starting with whatever manageable amount you can set aside. Treat that as a goal to build towards, not a condition you must satisfy before making progress.
In Fintrack, our category limits let you track spending in real time. Budget bars move from green to yellow to red as spending approaches the limit, while velocity alerts warn when your spending pace suggests you'll exceed a budget before month-end.
Our savings templates include emergency funds, vacation savings, and debt payoff. You can link budgets to savings goals so reduced discretionary spending supports a defined target.
Review your categories regularly and update them when work, health, or family circumstances change. The point isn't to prove every want was unnecessary; it's to keep essential spending protected while making deliberate room for enjoyment and future goals.
Fintrack offers budget planning tools for setting category limits, tracking spending, and linking budgets to savings goals. Visit Fintrack to set your first needs-first category limits and connect them to an emergency fund or another goal that matters to you.